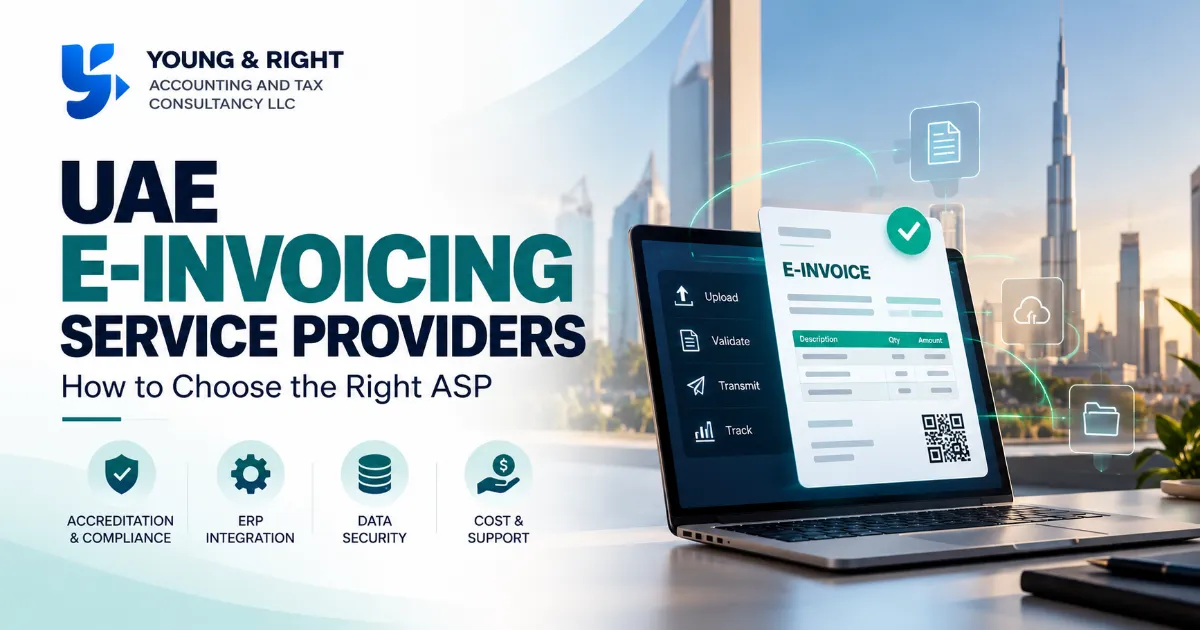
UAE E-Invoicing Service Providers: How to Choose the Right ASP in 2026
09/10/2026
From corporate tax registration to audits and bookkeeping, Young & Right offers personalized solutions that keep your business compliant and stress-free. Let’s take the complexity off your plate—starting with a free consultation.
Book Your Free Consultation
Effective tax planning isn't just about saving money today — it's a long-term strategy to build wealth, maintain financial security, and ensure compliance with tax laws. If you'd like details on how to implement a personalized tax plan, Young & Right can provide more information. Tax planning presents numerous significant advantages for both individuals and businesses. The following are some of the most notable benefits: 1. Decreases Tax Liability Lowers taxes owed: By utilizing available tax deductions, credits, and exemptions, one can decrease taxable income and lessen the overall tax burden. Enhances application of tax regulations: Strategic contributions to retirement accounts, health savings accounts (HSAs), and education-related credits can lead to substantial reductions in tax obligations. 2. Increases Savings and Cash Flow Retains more funds: Reduced tax payments result in increased cash flow for personal expenditures, investments, or reinvestment in business operations. Encourages long-term financial growth: Ongoing tax reductions enable the reinvestment of savings, fostering wealth accumulation and the achievement of financial objectives. 3. Ensures Adherence to Tax Regulations Prevents penalties and fines: Effective planning guarantees timely submissions and accurate payments, thereby minimizing the likelihood of audits, penalties, or fines. Adjusts to evolving tax regulations: Given the frequent changes in tax laws, planning allows individuals and businesses to remain informed about new regulations that may impact their tax responsibilities. 4. Aids in Retirement and Estate Planning Facilitates retirement savings: Contributions to retirement plans (such as 401(k)s or IRAs) are typically tax-deferred, which lowers current taxable income while building a retirement nest egg. Assists with estate planning: Thoughtful planning can mitigate estate taxes and ensure a seamless transfer of assets to heirs. 5. Offers Investment Advantages Management of capital gains: Strategic timing of asset sales can help minimize capital gains taxes. 6. Promotes Business Growth and Development Tax-efficient business practices: Businesses can take advantage of deductions for expenses such as equipment purchases, employee wages, and marketing efforts. Lowers overall operational costs: Optimizing business-related deductions can decrease expenses, enhancing profitability. 7. Supports Better Financial Decision-Making Enables better budgeting: When you know your after-tax income, it’s easier to plan for expenses, savings, and investments. Reduces stress and uncertainty: Proactive tax planning reduces last-minute filing stress and provides clarity on future tax obligations.
Take control of your UAE Corporate Tax obligations with strategic tax planning. Identify eligible deductions, improve tax efficiency, manage cash flow, and reduce compliance risks with professional support.
Get Expert Tax Planning Support