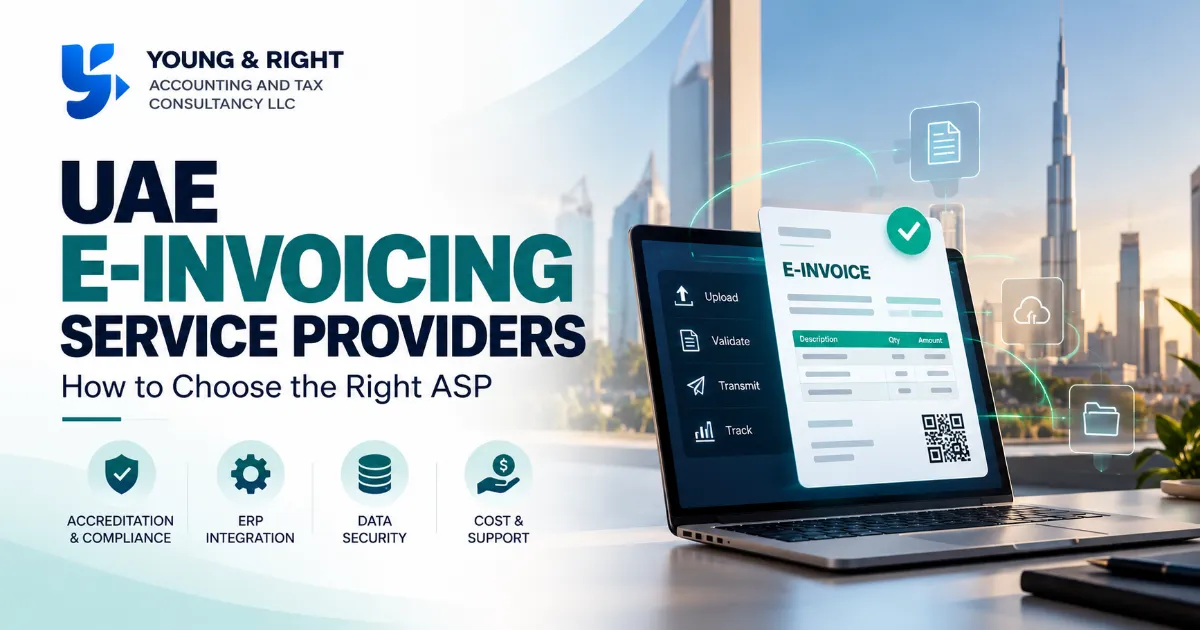
UAE E-Invoicing Service Providers: How to Choose the Right ASP in 2026
09/10/2026
From corporate tax registration to audits and bookkeeping, Young & Right offers personalized solutions that keep your business compliant and stress-free. Let’s take the complexity off your plate—starting with a free consultation.
Book Your Free Consultation
The United Arab Emirates issued Federal Decree-Law No. (47) of 2022 concerning the Taxation of Corporations and Businesses (hereinafter referred to as the ‘Decree law’) on 09 December 2022. • The CT Decree-law provides the legislative basis for the introduction and implementation of a Federal Corporate Tax (‘CT’) in the UAE and is effective for financial years starting on or after 1 June 2023. • Rationale for introducing a Federal CT regime is as under: To assist the UAE in realizing its strategic goals and to expedite its development and transformation. The assurance of a competitive Corporate Tax framework that complies with international standards, combined with the UAE's broad array of double tax treaties, will solidify the UAE's status as a premier destination for business and investment. To leverage global best practices and integrate widely recognized international principles, while reinforcing the UAE's status as a premier international business hub and a leading global financial center. The establishment of a federal corporate tax framework will enable the UAE to align with its commitment to the global minimum effective tax rate, as outlined in "Pillar Two" of the OECD's Base Erosion and Profit Shifting initiative. • The Ministry of Finance (MOF) and the Federal Tax Authority (FTA) have, to date, published the Corporate Tax Decree Law, a set of Frequently Asked Questions regarding Corporate Tax, as well as various Cabinet and Ministerial Decisions.
Get a clear overview of UAE Corporate Tax, including key rules, rates, exemptions, Free Zone provisions, and compliance requirements for businesses.
Explore Corporate Tax